Robustness
Monte Carlo to see the spread of outcomes, walk-forward so you never tune on the same stretch you evaluate, and parameter sensitivity to know whether the edge is real or a spike.
Product
ProductCharts, drawings, layouts and alerts in one workspace.BacktestingBar-by-bar tests that can't see the future.Deepwick ScriptRuns a subset of Pine Script.Get started freeFree account with an email link. No password.Community
Community scriptsIndicators and strategies other traders published.ExploreIdeas, scripts and backtests people share.Find tradersProfiles of the traders behind the scripts.Resources
BlogGuides on charting and backtesting.Script referenceEvery function the script engine supports.FAQPlans, data, privacy and how things work.DevelopersREST API, webhooks and tokens.SupportAsk a question or report a problem.StatusLive health of the data feeds and the app.Quant
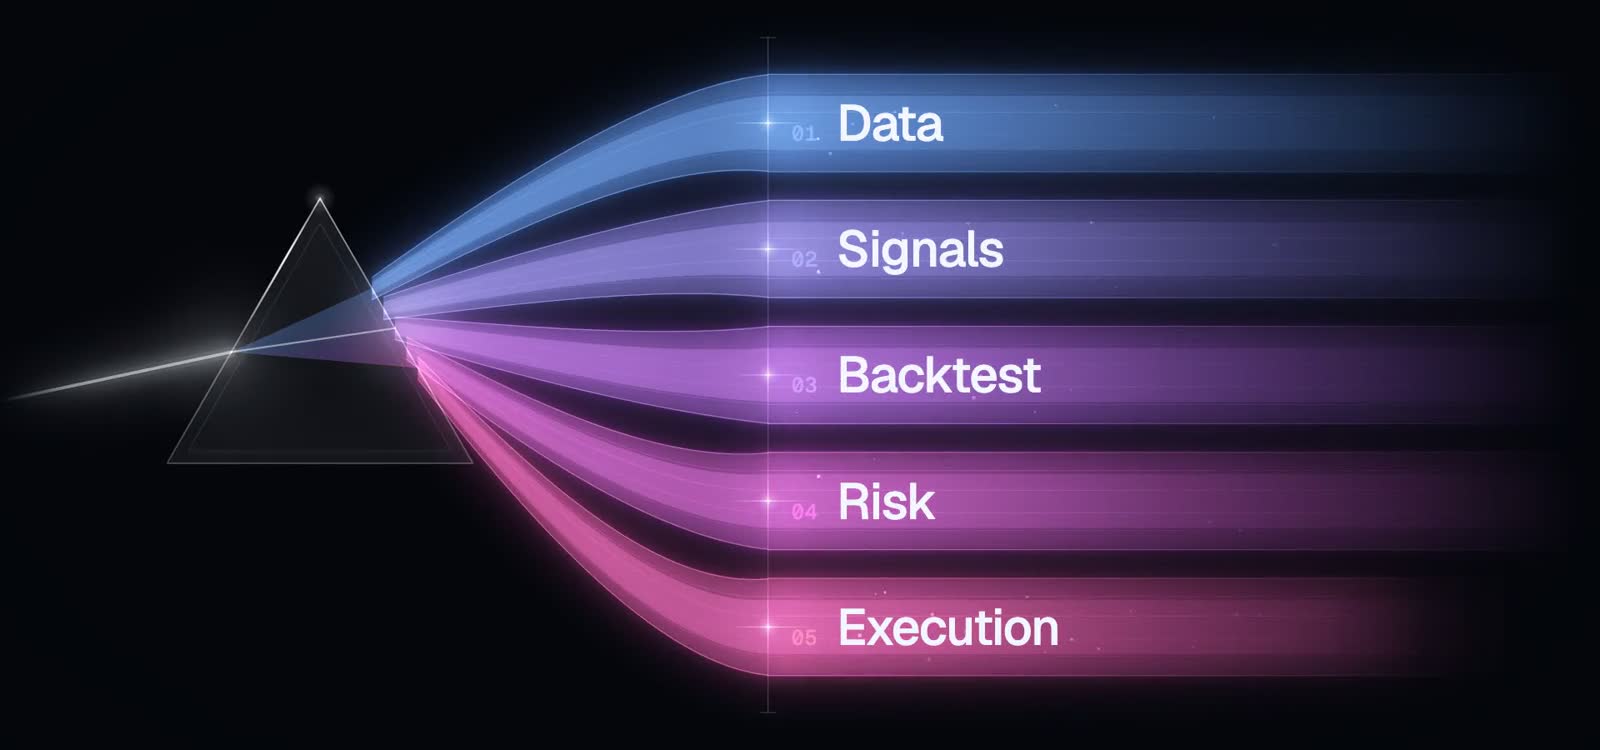
From the data to the execution: real price history, your signal in Pine Script, a backtest that never sees the future, risk numbers you can audit, and the exit to your broker. All on the same engine.
Nothing here is a black box: every stage says what it used and what it did.
Real history, minute by minute: M1 from 2003 on XAUUSD and forex, plus Binance spot pairs and USD-M perpetuals. No synthetic feed, no filler candles.
Your strategy, in the subset of Pine Script Deepwick runs. If it compiles in Pine it compiles here: same syntax, same functions.
Bar by bar, with no lookahead: every order fills on the next open, stop and target walk the path inside the bar. With the real spread, slippage and commission.
Net profit, profit factor, win rate, max drawdown, Sharpe and Sortino, buy & hold and exposure. Then Monte Carlo, walk-forward and parameter sensitivity.
When the signal passes your filter it goes on its own: alerts to Telegram, Discord or email, and a webhook to your broker or your terminal.
Quant
The same backtest answers different questions without rewriting the strategy.
Monte Carlo to see the spread of outcomes, walk-forward so you never tune on the same stretch you evaluate, and parameter sensitivity to know whether the edge is real or a spike.
Parameter sweeps on the same engine, with the cost inside the calculation. What wins the sweep still has to survive the walk-forward.
Loss distribution, not just the final number: where the drawdown concentrates, how much a worst streak costs and how much of it the spread explains.
Free plan, no card required. Sign up with your email to get started.
Built by a solo trader-developer. Shipped weekly.